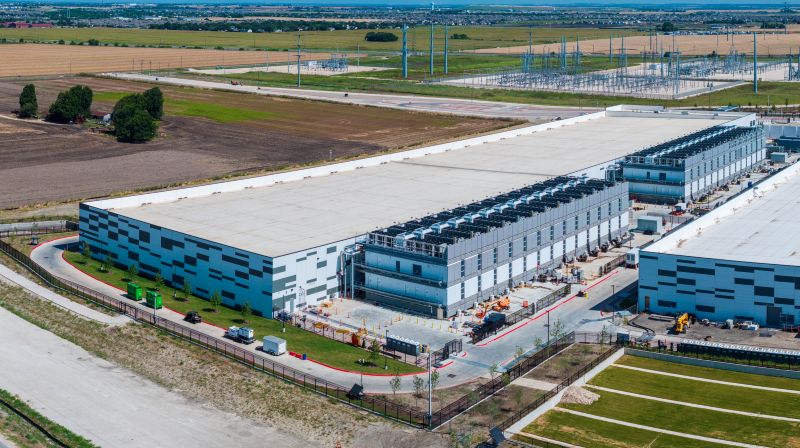
Elk Grove Village bills itself as the data center capital of the Midwest and Illinois runs on a grid in which nuclear supplies roughly a third of generation, according to ComEd data cited by CBRE. By JLL‘s count, the state has also watched at least $200 billion in data center projects originally planned for Illinois get built somewhere else.
Andy Cvengros, Executive Managing Director and Co-Lead of JLL’s U.S. Data Center Markets team, said those projects have landed in southern Wisconsin, northwest and northeast Indiana, Des Moines, Kansas City and Dallas. The physical case for Chicago, in his view, was never the problem.
“From a pure power standpoint, Illinois is actually an excellent market for data centers — we have strong generation capacity, a lot of nuclear and good green energy attributes,” Cvengros said.
The misses come against record national demand. JLL’s North America Data Center Report for midyear 2026 puts first-half absorption at 25 gigawatts with 66 gigawatts under construction and 95% of that pipeline precommitted. North American vacancy has held below 1% for a third straight year. Indiana and Ohio both appear among JLL’s top 10 markets by existing and under-construction capacity. Illinois does not.
The report tracks Chicago at 1,352 megawatts of existing inventory and northern Indiana at 1,206 megawatts, a market Cvengros said did not exist two years ago. Hyperscalers build in availability zones, three geographically distinct sites in a region that back each other up, and that footprint was always meant to include Illinois.
“When those Illinois projects got canceled, the hyperscalers didn’t go far — they went to Northwest Indiana instead, because it checked the same boxes,” Cvengros said.
Land is cheaper, Indiana passed comparable tax exemptions and the sites sit about 25 miles from downtown Chicago.
Cvengros points first to Illinois’ Biometric Information Privacy Act, which he said has created enough uncertainty around how AI data is handled that hyperscalers have pulled back or canceled major projects. He also cited ComEd’s higher deposit requirements and slow power procurement. Kelly Disser, Executive Vice President with the Industrial Services Group of NAI Hiffman, called ComEd’s cluster studies a significant consideration, with developers now underwriting application costs and the price of added generation, though he described BIPA as a consideration rather than a primary driver. CBRE’s Chicago H1 2026 report also cites anticipated BIPA revisions as pushing hyperscalers toward friendlier markets.
Then, on July 1, Illinois paused its data center incentive program. CBRE reports the pause runs through the mid-November veto session when Gov. JB Pritzker plans to push a broader regulatory framework and that applications filed before July 1 are unaffected.
For industrial owners, the competition is already priced in. Cvengros said the core corridors of Franklin Park, Northlake, Elk Grove and Aurora overlap heavily with where data center developers want to be and data center land comps have run about twice what industrial users pay. In Elk Grove, industrial land traded around $25 per square foot for years while data centers paid closer to $50, which he said has lifted the floor for the whole corridor and led to entire neighborhoods being acquired.
“Part of that is just a different business model — we’re not pricing projects by the square foot, we’re pricing them by megawatts of power,” Cvengros said.
Converting existing industrial buildings rarely works. Cvengros cited Skybox Chicago I, a 30-megawatt, 190,000-square-foot facility in Elk Grove Village, as a rare example, noting most conversions fail on sealed dock doors, roof reinforcement and a six-inch slab that needs to be 12.
Disser said qualifying sites are rare, which is exactly why they are valuable.
“We have three industrial developments underway now in western suburbs – not one of them is viable for a data center development,” Disser said.
The activity he does see is moving southwest toward Joliet and Minooka and into rural sites of 500 to 1,000 acres next to heavy power infrastructure, where added generation could take five or six years and natural gas is being explored. CBRE lists a planned 1-gigawatt Aligned campus in Coal City and a 1-gigawatt Tract campus in Morris, and puts Chicago-area vacancy at 2.2% with no contiguous block of 5 megawatts or more available this year.
JLL’s report floats a scenario in which demand normalizes around 2030. Cvengros is not convinced, saying supply coming online from 2028 through 2031 is largely pre-leased or soon will be.
“A lot of people are talking about a bubble,” Cvengros said. “We’re not seeing it. There is a capped ability to accommodate demand because of power availability, zoning timelines and everything that comes along with that.”