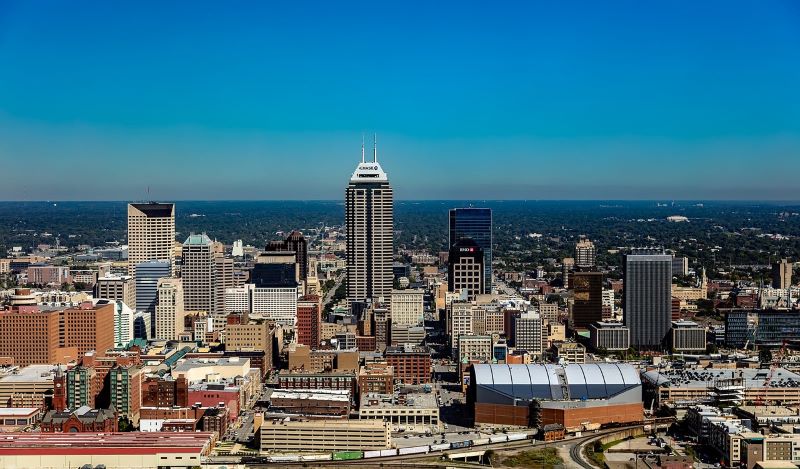
Indianapolis has long been recognized as a thriving hub for third-party logistics providers (3PLs). It stands to reason given the features that fundamentally attract all types of distribution and fulfillment operations: the efficient reach of the US population due to Indianapolis’ position on a map, the cross-country interstates that intersect the market, major parcel shipping hubs, a robust labor market, inexpensive real estate, and economic incentives.
3PLs have made a significant impact to the industrial real estate landscape since the 1990s. It’s difficult to accurately say how many facilities are actually operated by 3PLs in some capacity but we can measure how many facilities are leased by 3PLs on behalf of their underlying customer(s). Nearly 10% of the overall industrial real estate market is either leased or owned by 3PLs which is worthy of tracking their current leasing trends.
Steve Schwegman, JLL executive managing director
While there are several factors we could consider, we’ll focus on just three observations:
- The migration and location diversification of 3PLs across Indianapolis submarkets,
- Occupancy structures used to become more financially competitive and
- Recent overall slow-down of leasing activity.
Migration
In Indianapolis, the rise of the 3PL industry coincided with the spec development boom in/around Plainfield in the 1990s and 2000s. Therefore, many 3PLs set up their first operations in the Hendricks County submarket. As those 3PLs continued to grow with new and expanding customers, that growth occurred in and around the same submarket. It made operational sense to keep facilities close to one another to share management/ labor and to offset customer space needs with counter-seasonal inventories. Competition for labor wasn’t nearly as concerning then as the typical distribution center was handling a less labor-intensive throughput and therefore didn’t require as many employees as the more sophisticated distribution and fulfillment centers do today.
While Hendricks County still boasts the most space occupied by 3PLs, a trend started taking place in the mid to late 2010s to diversify submarket locations primarily driven by labor needs. Of lesser importance, the occupiers were also drawn to geographic diversity for natural disasters as well as the ability to offer slightly different logistical priorities (e.g. having new locations closer to parcel shipping hubs or different interstates).
Moving into the 2020s, the preferred submarkets have spread more evenly across the Indy MSA with Hendricks County and Johnson County accounting for approximately 30% of new 3PL lease activity each followed by Hancock and Boone Counties at roughly 15% of new 3PL leases each. Conversely, the renewal lease activity in the same years is still highly concentrated in Hendricks County (60%)
Outlook: We expect the submarket diversification to continue. Hancock County may be the biggest beneficiary due to the supply of available real estate and the (relatively) low competition for East Indy labor pools.
Occupancy Structures
A traditional, direct lease with a developer/landlord has been and still is the most common structure for 3PLs in Indianapolis. That said, it is important to note an increase in more creative and lucrative financial structures to gain a competitive edge over peers, increase profitability and provide customers with lower operating costs.
Purchasing (or having the ability to purchase) a facility for a dedicated customer contract has become a more popular request by 3PLs. The end game is not necessarily to own the facility long-term but rather a mechanism to create immediate up-front capital by securing a market purchase price and monetizing the value of a term lease with a credit 3PL tenant.
This trend was certainly more feasible and lucrative when rental rates were rising, and cap rates were falling rapidly. From the time a building was placed under contract to the time a lease was signed and the building “flipped” to an investor, the profitability only got better. In other words, time was an ally, not the enemy.
Today, it’s become more difficult to underwrite this type of structure as both rental and cap rates have leveled, and vacant building shells are at elevated construction pricing. Thus, a different type of structure has emerged: inflated tenant improvement allowances and/or other concessions.
We’re seeing a noticeable increase in requested (and achieved) TI allowance amounts. It has become more common by 3PLs to request to be able to use these allowances for relocation costs, personal property or even toward rent. This can benefit both developer and 3PL by holding rents firm and by offsetting startup costs, respectively.
Outlook: while a purchase/flip scenario might not be as feasible in the current climate, expect 3PLs to still request an option to purchase so they can capitalize on their tenancy when the time is right. Also watch for TI dollars to continue to climb on traditional lease transactions.
Overall Leasing Slowdown
Between the years 2020-2023, 3PLs accounted for an average of 4.1 million square feet of new (non-renewal) leasing activity per year. The historical peak occurred in 2022 with just over 8 million square feet taken down by 3PLs. As of mid-year 2024, a mere 260,000 SF of new leasing activity has occurred with several spaces being vacated and/or offered for sublease causing negative net absorption within the 3PL vertical.
Much of the reason for the slowdown is that many 3PLs were compelled to accept space and term risk during the height of tenant demand. In other words, taking on more space or lease term than their anchor customer required. This caused “shadow space” meaning space that was under lease but not occupied by customers. 3PLs of every size have encountered this with the larger companies using the shadow space to fulfill other customers and many of the smaller companies giving space back in the form of sublease or default.
Because of the shadow space phenomenon, the 3PL activity may be materially understated as no new leases are being signed but new and expanding accounts may be filling these voids internally.
A less significant reason for the slower leasing velocity are the occupiers opting to sign their own leases but hire a 3PL purely for operations. In these instances, the 3PLs are still very much active but causes a perception of slower leasing activity simply because of the entity signing the lease.
Outlook: We expect to see a continued increase in leasing activity from 3PLs in Indianapolis. While the real estate market is cyclical, industry leasing trends tend to return to the mean. As shadow space voids are filled and the general market improves, it seems reasonable that we could see a jump to 3 to 4 million square feet of new leasing activity from 3PLs as early as 2025. Most importantly, Indianapolis’ fundamentals remain incredibly strong to support and grow major 3PL hubs.
Steve Schwegman is executive managing director with JLL.


