Houston’s industrial market is attracting fresh attention from manufacturers and institutional investors, with major production projects, port infrastructure improvements and rising sales activity helping shape the outlook for the region, according to the latest research from Marcus & Millichap.
In its fourth-quarter 2026 Houston industrial market report, Marcus & Millichap cited expanding manufacturing investment and transportation infrastructure as important drivers of future demand. The northwest and northeast corridors are particularly well-positioned to benefit, as companies look for industrial space near major production facilities and transportation routes, according to Marcus & Millichap’s report.
The region’s port infrastructure is another significant advantage. Cargo moving along the Houston Ship Channel generated nearly $987 billion in economic impact nationwide in 2025, according to Marcus & Millichap. Ongoing channel-widening and deepening projects, combined with $2.1 billion in planned landside terminal investment over the next five years, should increase cargo capacity and help reduce transportation bottlenecks.
Additional bridge and roadway improvements could further strengthen demand for warehouses, distribution centers and manufacturing facilities near the port and major transportation corridors.
Manufacturing investments are also expanding the region’s industrial footprint. Apple’s planned expansion and Foxconn’s new facility in the northwest corridor are expected to support advanced manufacturing and engineering employment. Eli Lilly’s $6.5 billion project in the northeast corridor could extend industrial development into additional areas, creating opportunities for suppliers, service providers and logistics companies seeking locations near major production facilities.
Those investments are already helping shape local market conditions. The northeast corridor recorded a 200-basis-point decline in vacancy over the past year, while the northwest maintained a vacancy rate below the metro-wide average despite a recent wave of new construction.
Construction pipeline remains active
Houston continued to add industrial space during the first half of 2026. Industrial deliveries totaled 10.5 million square feet during that period, exceeding the comparable period a year earlier, according to Marcus & Millichap.
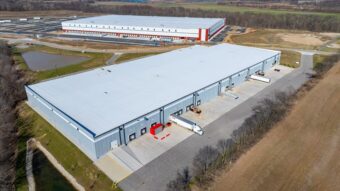
Much of the space scheduled for completion during 2026 is concentrated in the northwest corridor, particularly along U.S. Highway 290. A nearly 1.3 million-square-foot Grainger distribution center accounted for a significant portion of that corridor’s construction activity.
Other areas are expected to see less new development. The southeast and northeast corridors, along with Liberty County, are anticipating some of the largest reductions in annual deliveries.
The report forecasts an additional 23 million square feet of industrial construction for the Houston market in 2026, representing a 3.2% year-over-year increase in inventory.
Employment growth should provide additional support for industrial demand. Houston employers added 30,200 jobs during the first eight months of 2026, based on initial estimates. Professional and business services led hiring, while construction also posted notable growth. That activity could generate demand from contractors, suppliers and building-material distributors while supporting transportation and warehousing employment.
Vacancy and rents reflect shifting conditions
Houston’s industrial vacancy rate stood at 7.4% in June, up 20 basis points year-over-year, according to Marcus & Millichap. However, strong net absorption and fewer deliveries helped several submarkets record improving conditions.
The northeast and southwest corridors each experienced vacancy declines of 200 basis points or more. Vacancy in the northeast reached 7.6%, while the southwest posted a 5.3% rate, the lowest among local submarkets with more than 5 million square feet of inventory. Leasing activity in the southwest was concentrated near the intersection of Business U.S. Highway 90 and Interstate 610.
Average asking rents increased nearly 6% year-over-year as of June. The southwest’s declining vacancy helped support strong rent growth, leaving it with one of the metro area’s highest average asking rents. The northeast could see further rent increases as fewer deliveries coincide with falling vacancy.
For year-end 2026, Marcus & Millichap forecasts average asking rents of $10.20 per square foot, a 1% annual increase, and a metro-wide vacancy rate of 7.3%.
Investors return to the market
Industrial property sales also gained momentum. Transaction activity increased 40% year-over-year as of June, while dollar volume rose 30%, according to the report. Smaller properties helped drive the increase, with transactions involving properties priced between $1 million and $10 million climbing 45%.
Pricing remained firm. The average sale price per square foot increased 2% year-over-year, while the mean capitalization rate held steady in the lower-to-mid-7% range.
The northwest corridor led the region in trading activity, with transactions increasing 55% and accounting for 30% of all sales. Institutional capital contributed to the momentum, as more than half of the properties traded in the corridor changed hands as part of larger portfolio deals. Investors showed particular interest in properties along U.S. Highway 290, especially between Texas Highway 6 and Interstate 610.
The north corridor also recorded a nearly 50% increase in sales velocity. Properties smaller than 50,000 square feet represented about 70% of transactions there, and portfolio sales accounted for just over half of those trades. Many of the properties were located near Interstate 45 and State Highway 8.